QOF Real Estate Investment: The Substantial Improvement Test Explained
The substantial improvement test decides which QOF buildings qualify. See the doubling rule, the 30-month window, the rural 50% cut, and worked examples.
The Substantial Improvement Test That Every Opportunity Zone Real Estate QOF Must Pass
Buying an existing building through a Qualified Opportunity Fund sounds simple until the substantial improvement rule appears. The statute refuses to reward investors for passively holding old structures. Every existing building must be meaningfully improved within a strictly defined window.
This test kills more Opportunity Zone deals than any other qualification rule. Underwriting that ignores it produces tax surprises measured in full fund disqualification. This guide breaks the test into numbers, deadlines, and practical structures.
The 2025 tax act also added a rural relief provision that changes old math. Existing structures in rural zones now qualify at half the former spending threshold. Both versions of the test appear below with worked examples.
The statutory foundation sits in Section 1400Z-2(d) as amended by the 2025 act. Our QOZ deferral mechanics guide covers the program basics. Here the lens narrows to real property.
A quick map of the journey helps set expectations. The sections below cover the standard doubling test, the measurement window, the new rural relief, and the aggregation traps. A worked side-by-side example closes the loop with real numbers.
Why the Improvement Test Decides Real Estate Deals
Qualified opportunity zone business property must satisfy one of two origin stories. New construction automatically qualifies because the property has original use in the zone. Purchased existing buildings must instead pass the substantial improvement test.
Congress wanted capital that changes neighborhoods, not capital that just changes owners. The improvement requirement forces genuine renovation into every acquired-property deal. Ground-up construction sidesteps the test but carries entitlement and timeline risk.
Three conditions define qualifying business property in any zone. Meet all three and the property carries the program's benefits.
The QOF must acquire it by purchase after the zone's applicable start date. Original use must begin in the zone, or substantial improvement must occur. Substantially all of the property's use must also stay inside the zone.
Most renovated-deal failures trace back to one of two places. Either the improvement math falls short of the threshold, or the spending misses the window. Both failures are preventable with early planning.
Investors sometimes assume deferred gain itself funds the improvements. The deferral is a tax mechanism, not a source of project cash. Actual capital still has to arrive from investors, lenders, or reserves.
The Standard Test: Doubling the Building's Basis
The classic substantial improvement test works on the building alone. Land value sits completely outside the calculation, which surprises many investors. Only the adjusted basis of the existing structures counts toward the threshold.
During any thirty-month period, the QOF's additions to basis must exceed the building's adjusted basis. Practitioners call this the doubling requirement because the spending must exceed what the seller's basis reflects. Land costs, acquisition price allocation, and financing costs never count toward the additions.
A concrete example shows the arithmetic in action. A fund buys a property for $3 million, allocated $1 million to land and $2 million to the building. The improvement threshold is $2 million of qualifying additions.
Hard construction costs, architectural fees, and properly capitalized improvements all count. The fund can satisfy the requirement with renovation, expansion, or structural work. Cosmetic refreshes that never reach the dollar threshold fail the test entirely.
Capitalization rules decide which invoices count toward the additions. Costs must be chargeable to the capital account of the property to qualify. Repairs expensed under the repair regulations never help the improvement math.
| Deal component | Amount | Counts toward test? |
|---|---|---|
| Purchase price allocated to land | $1,000,000 | No |
| Purchase price allocated to building | $2,000,000 | Sets the threshold |
| Hard construction costs | $1,400,000 | Yes |
| Architectural and engineering fees | $350,000 | Yes |
| Site landscaping and hardscaping | $400,000 | Yes |
In this example, qualifying additions total $2.15 million against a $2 million threshold. The property passes with $150,000 to spare. Underwriters build buffers exactly like this into every deal model.
The Thirty-Month Window and How Spending Counts
The improvement clock runs for any thirty-month period beginning after acquisition. Funds choose when the measurement period starts, which creates planning flexibility. Spending outside a chosen window does not count toward that window's test.
Phased developments can run multiple thirty-month windows across tranches. Each building or tract can carry its own measurement period under the final regulations. Sophisticated sponsors sequence acquisitions deliberately to match their construction schedules.
Pre-development spending often happens before the fund closes on the property. Careful structuring puts working capital inside the fund before acquisition. The working capital safe harbor gives funds thirty-one months to spend held proceeds on qualifying improvements.
Funds should document every safe harbor election in the entity records. The written schedule, the funding sources, and the spending timeline all belong together. Regulators read that packet first whenever the safe harbor gets questioned.
The safe harbor covers project timelines, permits, and construction draws. Documentation must show a written schedule and a consistent spending plan. Funds that treat the paperwork casually lose the protection when examined.
Improvement basis then depreciates on its own schedule once placed in service. The new additions receive fresh depreciable lives inside the zone property. That depreciation stream interacts with any rental activity the fund operates.
The Rural Cut: Fifty Percent of Adjusted Basis
The 2025 act halved the threshold for existing structures in rural zones. Improvement expenditures now qualify when they exceed 50% of the building's adjusted basis. The change took effect at enactment, so it applies immediately for qualifying rural property.
Run the earlier example again with a rural designation. The same $2 million building basis now carries a $1 million threshold. The $2.15 million of planned spending now doubles the required improvement level.
The relief only applies inside zones that qualify as entirely rural. The statute excludes cities or towns above 50,000 residents and adjacent urbanized areas. Our rural opportunity zone guide details that definition.
Rural developers should document the designation carefully at acquisition. The improvement relief and the 30% basis step-up both depend on rural character. Evidence assembled at purchase protects benefits claimed years later.
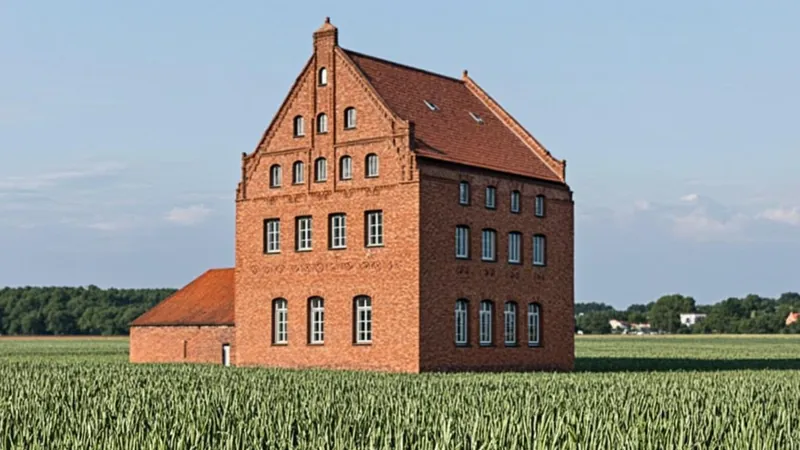
The relief also reshapes which rural buildings make sense to pursue. Larger structures with modest bases suddenly clear the qualification bar easily. Old warehouses and institutional buildings top the rural acquisition lists now.
What Counts, What Fails, and What Gets Aggregated
Several mechanical rules decide whether spending qualifies at all. The final regulations aggregate acquisitions between related parties, which limits basis-stripping strategies. Properties acquired from 20%-or-more related sellers face combined testing.
Leased buildings follow a parallel track with their own thresholds. A 90% test applies to the leased property's fair market value rather than basis. Long-term leases carry additional requirements measured across fifteen-year periods.
Vacant and abandoned buildings received helpful regulatory treatment on this front. Property unused for significant periods can count as having original use in the zone. Redevelopment of long-dark retail boxes benefits directly from that interpretation.
A short list of businesses can never qualify regardless of improvements. Golf courses, gambling facilities, liquor stores, and tanning salons remain excluded. Massage establishments and hot tub facilities round out the statutory exclusions.
Financing arrangements deserve a brief mention in the counting rules. Debt-financed improvements count fully when the fund properly capitalizes them. Interest during construction generally capitalizes into the project rather than counting separately.
A Worked Deal Example: Two Buildings Side by Side
Comparison clarifies how the same deal changes with geography. Two identical funds each acquire a $3 million property with a $2 million building basis. One sits in a metro zone and the other in a certified rural zone.
The metro fund must deploy at least $2 million of qualifying additions. Its capital plan allocates $1.1 million to construction and $650,000 to fees and site work. Total additions reach $1.75 million, which fails the threshold by a quarter million.
The rural fund faces only a $1 million threshold instead. Its identical $1.75 million plan passes with a $750,000 cushion. Both funds hold the same property economics, but only one qualifies for deferral.
The metro sponsor must either add spending or redesign the deal. Options include a larger renovation scope, a phased additional acquisition, or ground-up construction. Each path carries different timeline and return consequences.
This is exactly why improvement math belongs in the first underwriting pass. Tax qualification changes project feasibility, not just reporting. Run both thresholds through the real estate capital gains hub resources before committing.
The side-by-side also reveals the quiet state-level effects. Passing qualification in a high-tax state multiplies the value of deferral. Failing it leaves the investor with ordinary holding economics and no deferral at all.
When the Fund Sells Before the Ten-Year Mark
Not every real estate fund reaches its tenth anniversary. Early asset sales create inclusion events for investors holding interests. The deferred gain plus any appreciation on the sold portion becomes taxable.
Exit planning should appear in the operating agreement from the very start. Hold-versus-sell decisions after year ten carry no federal tax on appreciation anyway. Sponsors who document the exit logic protect investors from late surprises.
Refinancing adds one more exit-adjacent topic worth noting. Pulling cash out through debt does not trigger recognition by itself. Investors should still model the leverage against the fund's compliance posture.
The Compliance Calendar for Real Estate QOFs
Improvement spending sits inside a larger compliance rhythm. The fund must also maintain the 90% asset test on each monthly averaging date. Form 8996 certifies the fund, and Form 8997 tracks investor-level deferrals.
Missing the 90% test triggers a monthly penalty rather than instant disqualification. The penalty is monetary, but repeated failures invite deeper scrutiny from examiners. Strong funds document their monthly asset composition automatically.
Property-level records deserve the same discipline as fund-level filings. Construction draws, contractor invoices, and capitalized cost schedules all support the improvement claim. The examination question arrives years later, when memories and staff have changed.
Investors should receive an annual improvement status letter from the sponsor. The letter should state qualifying additions to date against the required threshold. Transparency during the hold prevents disputes at the exit.
Our rental property tax guide covers the depreciation side of the hold period. Depreciation on improved buildings interacts with the eventual disposition rules. Investors planning a ten-year exit should read both guides together.
One last comparison belongs in every investor's model. Higher earners also owe the 3.8% surcharge on recognized investment gains under current law. Deferral and exclusion both shrink that surcharge alongside the regular rate savings.
The substantial improvement test rewards sponsors who respect its arithmetic. Build the threshold, the buffer, and the documentation into the deal from day one. Funds that do so turn a strict gate into a routine milestone.
Rural buyers enjoy the easiest path the program has ever offered. The halved threshold converts marginal renovations into clean qualifications. That single change may redirect more capital than any headline provision in the law.

Wasim Akram
Wasim researches and writes every article on TaxGainsCalc, covering capital gains tax for everyday investors. Every figure is checked against primary IRS sources before it goes live.