Capital Gains Tax for Seniors & Retirees 2026: The Complete Guide to Paying Less
Complete 2026 guide to capital gains tax for seniors and retirees. Learn how the 0% bracket works, how capital gains affect Social Security taxation, retirement account withdrawal strategies, and which states are tax-friendly for retirees.

Retirees Have a Tax Advantage Most Do Not Know About
I sit down with retired couples all the time, and I hear the same worry over and over: "We are living on a fixed income, and now we have to pay tax on our investments too?" What most of them do not realize is that capital gains tax for seniors works differently than they fear — retired households often land in some of the best tax positions available, if you play it right.
Here is the thing. When you stop earning a salary, your taxable income often drops significantly. Social Security is only partially taxable. Pensions and retirement account withdrawals give you some control over how much income you recognize each year. And all of this can put you squarely in the 0% long-term capital gains bracket, meaning you pay zero federal tax on your investment gains.
But there is a catch. The same capital gains that could be tax-free can also push more of your Social Security into taxable territory. And if you are not careful about when and how you sell investments, you could end up paying more tax than necessary — sometimes thousands more.
This guide covers everything seniors and retirees need to know about capital gains tax in 2026. The 0% bracket, Social Security interaction, retirement account strategies, and the states that treat retirees best.
The 0% Capital Gains Bracket: A Gift for Retirees
The most important thing to understand about long-term capital gains tax is that there is a 0% bracket. If your total taxable income — including your capital gains — falls below certain thresholds, your long-term gains are completely tax-free at the federal level.
For 2026, the 0% bracket covers:
| Filing Status | Taxable Income Up To |
|---|---|
| Single | $49,450 |
| Married filing jointly | $98,900 |
| Head of household | $66,200 |
These numbers include all of your income — Social Security (the taxable portion), pensions, retirement withdrawals, interest, dividends, and capital gains. If the total is below the threshold, your long-term capital gains cost you nothing in federal tax.
Let me give you a real example. Harold is 71, single, and retired. He collects $22,000 in Social Security, takes $8,000 from his traditional IRA, and has $15,000 in long-term capital gains from selling stock.
After deductions and the Social Security tax calculation, his total taxable income comes to about $35,000. That is well below the $49,450 threshold.
His entire $15,000 in capital gains is taxed at 0%. He owes zero federal tax on those gains.
How to Maximize the 0% Bracket
The key is managing your total taxable income. Here are the strategies that work:
- 1Control your IRA and 401(k) withdrawals. You decide how much to take out each year. If taking less keeps you in the 0% bracket, do that. If you have Roth accounts, withdrawals from those are tax-free and do not count toward your taxable income at all.
- 1Time your stock sales. If selling $20,000 in stock pushes you above the 0% threshold, consider selling only $10,000 this year and $10,000 next year. Spreading gains across tax years can keep you in the 0% bracket both years.
- 1Use the standard deduction. For 2026, the standard deduction for singles 65 and older is roughly $16,550 (base $15,700 plus $1,650 age 65+ additional). For married couples both 65+, it is roughly $33,200. This means the first $16,550 of income for a single senior is effectively tax-free before the brackets even kick in.
- 1Take capital losses to offset gains. If you have some gains that fall in the 15% bracket, look for losing positions to sell. Tax-loss harvesting works the same way for retirees as it does for anyone else. Just watch out for the wash sale rule if you plan to repurchase the same security.
Is There a Special Capital Gains Exemption for Seniors?
Let me answer the question half of my retired clients ask in the first meeting. No — federal law contains no capital gains exemption based on age. Turn 65, 75, or 95, and the IRS taxes your gains exactly like everyone else's.
The confusion has deep roots. From 1964 until 1997, homeowners 55 and older could exclude $125,000 of home-sale gain once in a lifetime. Congress repealed that provision when it created today's Section 121 exclusion, which is better in every way — larger, and not limited to older sellers.
What seniors actually get is indirect, and it is real. Retirees with modest income fall into the 0% long-term bracket.
The Section 121 exclusion shelters most home sales. Heirs receive a step-up in basis on inherited assets. Age helps through the income side of the formula, not through an exemption.
How Capital Gains Affect Your Social Security Taxation
This is where many retirees get caught off guard. Capital gains do not just affect the tax on the gains themselves — they can also change how much of your Social Security is taxed.
The Social Security Tax Thresholds
The IRS uses something called "combined income" (also called provisional income) to determine how much of your Social Security is taxable. The formula is:
Combined income = adjusted gross income + nontaxable interest + half of Social Security benefits
Then the thresholds kick in:
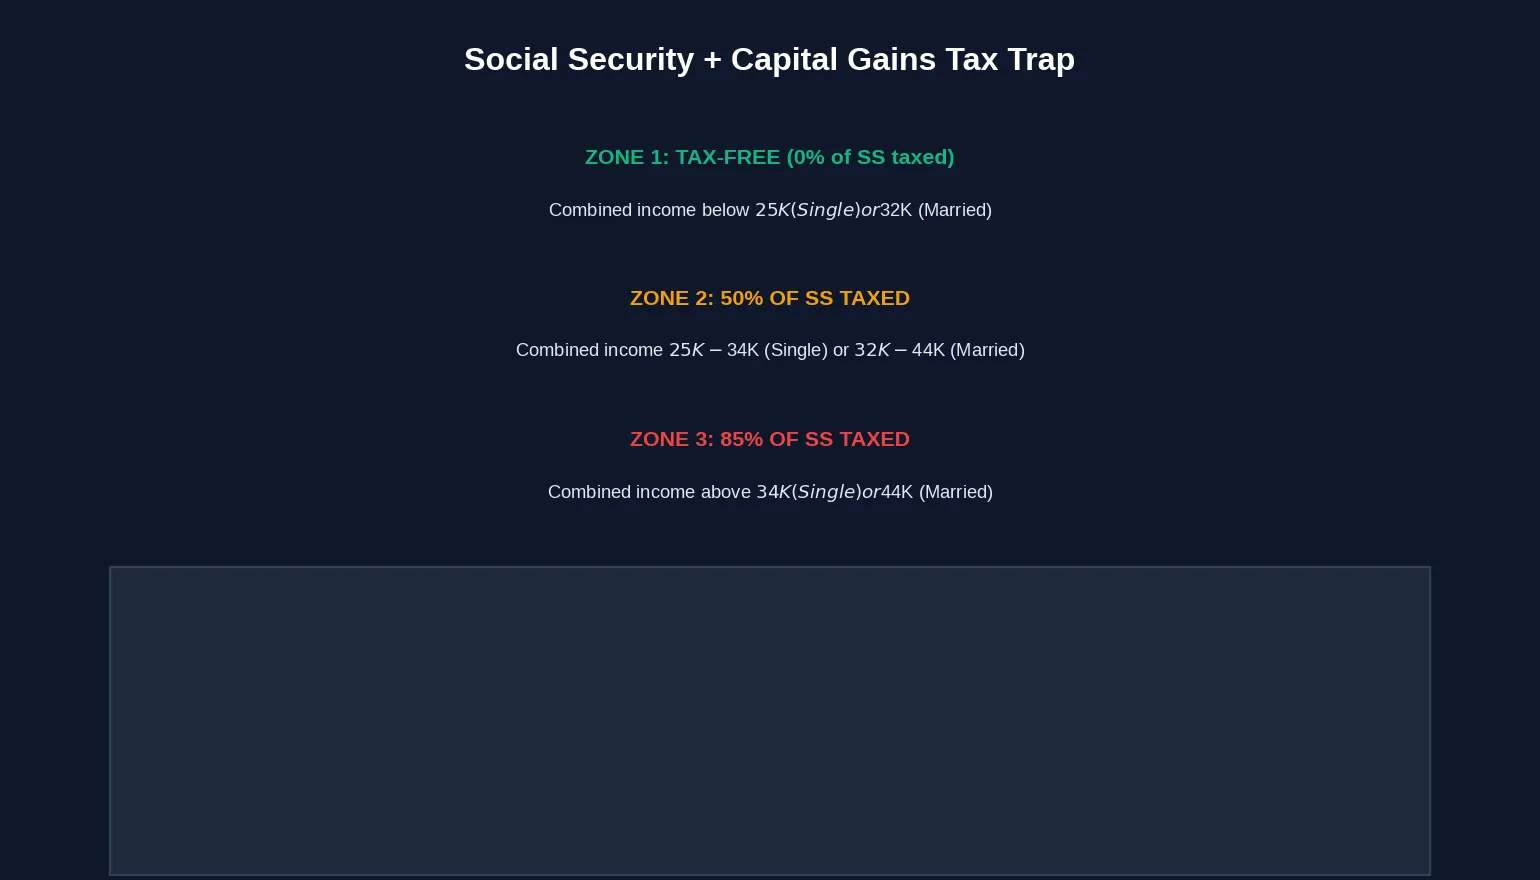
- Below $25,000 (single) or $32,000 (married): 0% of your Social Security is taxed. You keep every dollar.
- Between $25,000-$34,000 (single) or $32,000-$44,000 (married): Up to 50% of your Social Security is taxable.
- Above $34,000 (single) or $44,000 (married): Up to 85% of your Social Security is taxable.
These thresholds have not been adjusted for inflation since they were created in 1983 and 1993. That means more and more retirees get caught in them every year.
The Double Tax Hit
Here is the problem. When you realize a capital gain, it increases your adjusted gross income, which increases your combined income, which can push more of your Social Security into taxable territory. You are not just paying tax on the capital gain — you are also paying tax on Social Security that would have been tax-free otherwise.
This is sometimes called the "tax torpedo." A $10,000 capital gain might cause an additional $4,250 of Social Security to become taxable (moving from the 50% zone to the 85% zone). So you are paying tax on $14,250 instead of $10,000. That is a 42.5% increase in your taxable income from the same gain.
How to Avoid the Tax Torpedo
The solution is strategic timing. Here is what I tell my retired clients:
- 1Realize gains in years when your other income is low. If you have a year with minimal IRA withdrawals and no unexpected income, that is the year to sell appreciated stock.
- 1Use Roth conversions strategically. Converting traditional IRA money to a Roth increases your income in the conversion year, but Roth withdrawals are tax-free forever. This can reduce future required minimum distributions, which reduces future taxable income, which keeps your Social Security less taxed.
- 1Avoid large gains in a single year. Instead of selling your entire stock position at once, spread the sales over two or three years to keep each year's income below the Social Security thresholds.
- 1Consider state capital gains tax rates when choosing where to live in retirement. Nine states have no income tax at all, which means no state tax on your capital gains or your Social Security.
Retirement Account Withdrawals and Capital Gains
The way you withdraw money from retirement accounts has a direct impact on your capital gains tax situation. Here is how different account types work:
Traditional IRA and 401(k) Withdrawals
Every dollar you withdraw from a traditional retirement account is taxed as ordinary income. This is not a capital gain — it is ordinary income, and it increases your adjusted gross income, which can push more of your Social Security into taxable territory and push your capital gains out of the 0% bracket.
If you take a $30,000 distribution from your traditional IRA, that $30,000 stacks on top of your other income. It could be the difference between paying 0% and 15% on your capital gains.
Roth IRA and Roth 401(k) Withdrawals
Roth withdrawals are completely tax-free for qualified distributions (account open at least five years, age 59.5 or older). They do not count toward your taxable income at all. This makes Roth accounts incredibly powerful for retirees because you can withdraw money without affecting your Social Security taxation or your capital gains bracket.
If you have both traditional and Roth accounts, a smart strategy is to take just enough from the traditional account to stay in the 0% capital gains bracket, and cover the rest of your needs from Roth withdrawals.
Required Minimum Distributions (RMDs)
Starting at age 73, you must take RMDs from traditional IRAs and 401(k)s. These mandatory withdrawals can push your income up whether you want them to or not. The amount is based on your account balance divided by your life expectancy.
If your RMD is large enough to push you above the 0% capital gains bracket, you cannot avoid it — but you can plan around it. Take voluntary distributions in the years before RMDs kick in to reduce the eventual required amounts. Or convert some traditional money to Roth before age 73 to lower your traditional account balance.
Capital Gains When Selling Your Home in Retirement
Many retirees downsize or move in retirement. If you sell your primary residence, the Section 121 exclusion lets you exclude up to $250,000 (single) or $500,000 (married) of gain from tax, as long as you owned and lived in the home for at least two of the five years before the sale.
This exclusion can be a huge benefit for retirees who have lived in their homes for decades and built up substantial equity. For the full rules, our guide on capital gains tax when selling your home covers every requirement and exception.
What retirees often miss is that the home sale gain, even if excluded from capital gains tax, might still affect your Social Security taxation indirectly if any portion is taxable (gains above the exclusion limit). Plan the timing of a home sale just as carefully as you would plan a stock sale.
Inherited Assets and the Step-Up in Basis
One of the biggest tax breaks for seniors involves passing on appreciated assets. When you die, your heirs receive a step-up in basis to the fair market value on the date of your death. All the unrealized gains that accumulated during your lifetime simply vanish for tax purposes.
This means that holding highly appreciated stocks or real estate until death can be the best tax strategy of all. Your heirs could sell immediately and owe little or no capital gains tax. Our guide on capital gains tax on inherited property explains how this works in detail.
For retirees with large unrealized gains, this step-up in basis is a powerful reason to hold rather than sell. Instead of paying 15% or 20% on the gain now, you can let your heirs inherit the asset with a stepped-up basis and potentially pay 0% if their total income falls in the 0% bracket.
Best and Worst States for Retiree Capital Gains
Where you live in retirement matters enormously. Your state capital gains tax rate can range from 0% to over 13% on top of federal tax.
Tax-Friendly States for Retirees
These states have no income tax, which means no state tax on capital gains or Social Security:
| State | Income Tax | Social Security Taxed? |
|---|---|---|
| Florida | 0% | No |
| Texas | 0% | No |
| Nevada | 0% | No |
| Wyoming | 0% | No |
| Alaska | 0% | No |
| South Dakota | 0% | No |
| Tennessee | 0% | No |
| New Hampshire | 0% | No |
| Washington | 0%* | No |
*Washington taxes long-term gains above $270,000 at 7%, but does not tax Social Security.
States to Think Twice About
| State | Top Rate | Social Security Taxed? |
|---|---|---|
| California | 13.3% | No (but high tax on everything else) |
| New York | 10.9% | No (but NYC tax applies) |
| New Jersey | 10.75% | No |
| Oregon | 9.9% | No |
| Minnesota | 9.85% | Yes, fully taxed |
Minnesota is one of the few states that fully taxes Social Security benefits, making it particularly expensive for retirees. California does not tax Social Security, but its 13.3% top rate on other income including capital gains is the highest in the nation.
The Net Investment Income Tax for Retirees
The Net Investment Income Tax adds 3.8% on top of your regular capital gains rate if your modified adjusted gross income exceeds $200,000 (single) or $250,000 (married). Most retirees do not hit this threshold, but if you have a large capital gain in a single year — from selling a business, a rental property, or a large stock position — you could trigger it.
Combined with the regular 20% long-term capital gains rate and a high state rate, the total can be painful. A $500,000 gain in California could face a combined rate of roughly 37% (20% + 3.8% NIIT + 13.3% state).
Reporting Capital Gains as a Retiree
The reporting process is the same regardless of age. You report capital gains on Form 8949 and Schedule D. Our guide on how to report capital gains on your tax return walks through every form and line.
The one difference for seniors is the Form 1040-SR, which is designed specifically for taxpayers age 65 and older. It uses larger print and includes a chart for the standard deduction with the additional amounts for age 65+. The tax calculations are identical to the regular 1040.
Frequently Asked Questions
Is there a capital gains exemption for seniors over 65?
No federal exemption exists — age alone never changes the capital gains rate. Seniors save through the 0% long-term bracket when taxable income stays under $49,450 single or $98,900 married, through the Section 121 home-sale exclusion, and through the step-up in basis their heirs receive.
What are the 2026 income limits for the 0% capital gains bracket?
Taxable income up to $49,450 for singles, $98,900 for married filing jointly, and $66,200 for heads of household earns the 0% rate on long-term gains. Remember the gain itself counts toward taxable income, so a large sale can push you over the line mid-transaction.
Do capital gains make my Social Security taxable?
They can. Gains count in your provisional income, and crossing $25,000 single or $32,000 married starts taxing up to half of your benefits, with up to 85% taxable above $34,000/$44,000. A gain planned around those lines often costs far less than the same gain dumped on top of other income.
Do I pay capital gains tax when I sell my home after retiring?
Probably less than you fear. Section 121 excludes $250,000 of gain for singles and $500,000 for married couples when you owned and used the home as your primary residence for two of the last five years. Gains beyond that are long-term gains, usually at 15% or 20%.
Are IRA or 401(k) withdrawals taxed as capital gains?
Never. Traditional IRA and 401(k) withdrawals are ordinary income at your regular bracket, even if the account invested in stocks that grew for decades. Only taxable brokerage accounts produce capital gains — Roth withdrawals, qualified and after age 59½, are tax-free entirely.
What is the best state for retiree capital gains?
Nine states levy no wage income tax, and most also skip capital gains — Alaska, Florida, Nevada, New Hampshire, South Dakota, Tennessee, Texas, Washington, and Wyoming. Watch the fine print: Washington taxes high-end gains separately, and New Hampshire taxes interest and dividends no more since 2025.
The Bottom Line
Being retired gives you a real tax advantage on capital gains — but only with planning. The 0% bracket can wipe out federal tax on up to $98,900 of long-term gains for a married couple, provided total taxable income stays under the line. Most retirees never use it because nobody told them it exists.
Three traps deserve respect. The Social Security tax torpedo turns one careless sale into taxable benefits.
Retirement account withdrawals are ordinary income, not capital gains, no matter what the money is invested in. And no age-based exemption wipes the bill away at 65 — the levers that work are timing, the 0% bracket, Section 121, and the step-up at death.
The gap between a planned retirement and a drifting one routinely reaches five figures a year. For more walkthroughs, browse our full collection of capital gains tax articles and tips.
Fact-Checked & Reviewed
This article was written and fact-checked by Wasim Akram, Founder & Lead Researcher at TaxGainsCalc. Every rate, threshold, and rule referenced is verified against IRS publications and current tax law as of the date published. Tax laws change frequently — always consult a qualified tax professional for advice specific to your situation.
Disclaimer: This article is for informational purposes only and does not constitute tax, legal, or financial advice. Tax laws and regulations change frequently, and the information presented here may not reflect the most current updates. You should consult with a qualified CPA, tax attorney, or financial advisor before making any tax-related decisions. TaxGainsCalc is not responsible for any actions taken based on the information provided in this article.
Continue Reading
Wasim Akram
Wasim researches and writes every article on TaxGainsCalc, covering capital gains tax for everyday investors. Every figure is checked against primary IRS sources before it goes live.